Asian Forex Outlook: Dollar Strength Pressures Yen and Regional Currencies

Asian Currencies Mixed as Dollar Holds Near Two-Month High, Yen Weakens on BOJ Outlook
Asian currencies traded mixed on Thursday, October 1, as the US dollar remained near a two-month high, supported by elevated US Treasury yields and uncertainty surrounding the Federal Reserve’s interest rate outlook. The Japanese yen weakened after the Bank of Japan (BOJ) released a summary of its September policy meeting that revealed differing views on the pace of future interest rate increases.
Investors continued to assess the outlook for US monetary policy alongside developments in Japan, Australia, China and South Korea. While strong export figures provided an encouraging signal for South Korea, several regional currencies remained under pressure from the stronger dollar and shifting global investment flows.
Market figures in this report reflect the supplied market snapshot and should not be interpreted as live prices.
US Dollar Holds Firm as Treasury Yields Support Demand
The US Dollar Index (DXY), which measures the greenback against a basket of major currencies, stood at approximately 101.58, up 0.13% in the reported session. The index gained around 2% during September, recording its strongest monthly performance since June, according to the supplied market report.
Elevated US Treasury yields continued to support the dollar as investors evaluated inflation risks, government borrowing and the Federal Reserve’s next policy move.
Although weaker-than-expected US inflation reduced expectations of an October rate increase, uncertainty remains over the timing and extent of future monetary easing. Incoming inflation and employment data will be important in determining whether the Fed can ease policy or needs to maintain restrictive interest rates for longer.
Higher Treasury yields can make US assets more attractive to international investors, supporting demand for the dollar. However, exchange rates also depend on expectations for interest rates in other economies, market positioning and broader financial conditions.
Global bond markets also experienced significant pressure during September amid concerns about government finances, heavy debt issuance and renewed inflation risks. These developments contributed to changing expectations for borrowing costs across major economies.
Japanese Yen Weakens as BOJ Signals Differing Views on Rate Hikes
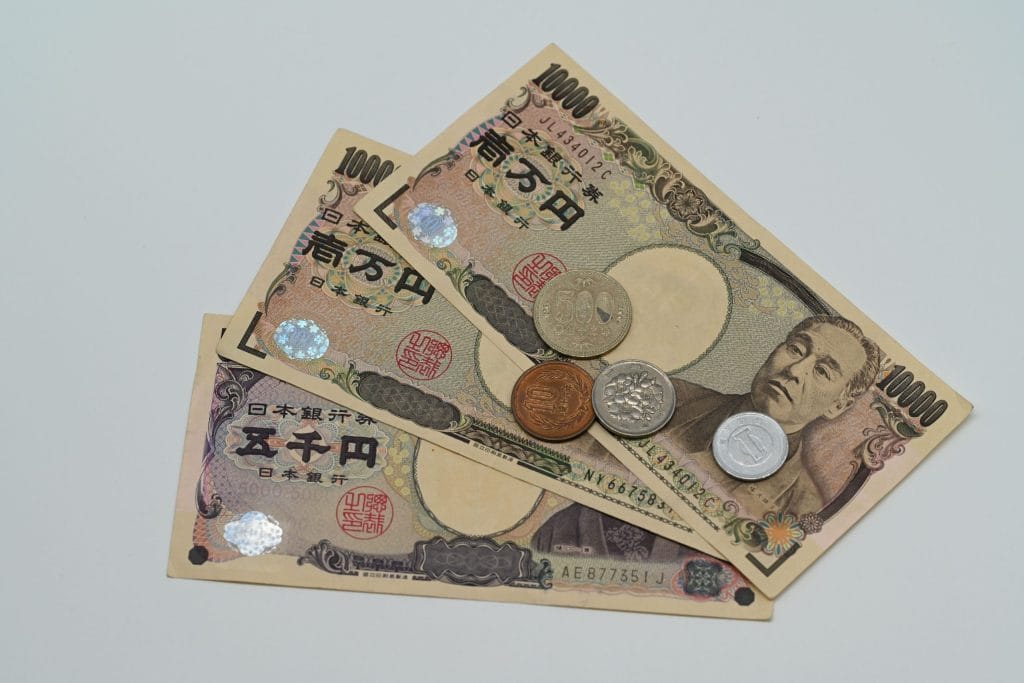
The US dollar rose approximately 0.5% against the Japanese yen to 158.15, while the yen had earlier weakened to around 158.21 per dollar, its lowest level in two weeks in the supplied market snapshot.
The movement followed the Bank of Japan’s release of its September policy meeting summary. The document highlighted differing opinions among policymakers about Japan’s economic momentum and the appropriate pace of further interest rate increases.
Some policymakers supported accelerating rate hikes or moving interest rates closer to their eventual target sooner. Others pointed to weaknesses in domestic demand and questioned whether economic activity was expanding strongly and sustainably.
The discussion reflects the challenge facing the BOJ as it balances inflation risks against uncertainty surrounding household spending, domestic demand and the wider economic outlook.
According to the supplied market report, market-implied expectations for a BOJ rate increase by October 30 had fallen below 20%, after exceeding 30% at one point on Wednesday. A December increase was described as fully priced into market expectations at the time.
These probabilities represent market pricing rather than a confirmed central bank decision and can change as new economic data emerge.
The interest rate differential between Japan and the United States remains important for the yen. If US yields remain elevated while Japanese rate increases proceed gradually, the difference in returns available on the two countries’ assets could continue to weigh on the Japanese currency.
Australian Dollar Under Pressure After Trade Surplus Narrows
The Australian dollar traded near $0.69 against the US dollar, close to a two-month low and below the $0.70 level.
Australia’s trade surplus narrowed to A$495 million in August from a revised A$1.35 billion in July. The result was significantly below economists’ expectations of approximately A$2 billion.
A narrower trade surplus can indicate a reduced contribution from net exports, although its economic significance depends on changes in both exports and imports.
The trade figures arrived after the Reserve Bank of Australia raised its cash rate by 25 basis points to 4.60% on September 29. The rate reached its highest level since 2011, according to the supplied report.
The decision highlights the challenge facing Australian policymakers as they attempt to address inflation while managing the effects of higher borrowing costs on household spending and business investment.
Despite the rate increase, the Australian dollar remained vulnerable to broad US dollar strength and uncertainty about the direction of global interest rates.
Investors will continue monitoring Australian inflation, employment and trade data for further indications of the Reserve Bank’s policy outlook.
Read more in the SkyPress Forex Markets section.
Chinese Yuan Steady Ahead of National Day Holiday
The US dollar rose approximately 0.1% against the offshore Chinese yuan to 6.72, while the onshore USD/CNY pair was little changed around 6.70.
The yuan recorded its seventh consecutive quarterly gain against the dollar in its final trading session before China’s National Day holiday, according to the supplied market report.
Mainland Chinese markets were scheduled to close from October 1 through October 7 and reopen on October 8. Hong Kong markets were also closed on October 1 for National Day.
Reduced trading activity can affect liquidity across regional foreign exchange markets. With fewer market participants active, individual transactions and developments in major currencies can sometimes have a greater influence on short-term price movements.
Investors will also monitor China’s economic performance, trade conditions and policy developments for indications of the yuan’s direction after markets reopen.
South Korean Exports Surge, but Won Remains Under Pressure
South Korea reported a sharp increase in exports in September, with shipments rising 83.5% year-on-year to a reported record monthly value of US$120.9 billion, according to figures attributed to Yonhap News Agency.
Semiconductors were a major contributor to the increase, with chip exports reportedly exceeding US$60 billion for the first time amid strong demand and higher prices.
Imports also increased, rising 26% year-on-year to approximately US$71.09 billion. The resulting trade surplus reached a reported record of about US$49.85 billion.
Despite the strong export performance, the South Korean won remained under pressure. The USD/KRW pair rose around 0.2% to 1,359.80 in the supplied market snapshot, indicating weakness in the won against the dollar.
Strong exports can support a currency by generating foreign-currency receipts and reflecting demand for domestic goods. However, currency movements also depend on capital flows, investor positioning, interest rate expectations and broader US dollar movements.
Market commentary cited in the supplied report suggested that changing portfolio flows and reduced currency-hedging activity could limit the won’s ability to extend previous gains.
The export figures provide a significant indication of external demand, particularly for semiconductors, but they do not guarantee appreciation in the won.
Other Asian Currencies Show Mixed Performance
Elsewhere in the region, the US dollar strengthened against several currencies as higher US yields and broad dollar demand influenced trading.
- Indonesian rupiah: USD/IDR rose approximately 0.67% to 17,949, with the rupiah facing pressure from the stronger dollar, elevated US yields and high oil prices.
- Singapore dollar: USD/SGD increased around 0.16% to 1.2795.
- Indian rupee: USD/INR edged down approximately 0.02% to 96.09.
- New Zealand dollar: NZD/USD declined around 0.14% to $0.57.
A stronger US dollar can raise the local-currency cost of imports and dollar-denominated debt for some economies. Higher oil prices can add further pressure for countries that rely heavily on imported energy.
Nevertheless, each currency’s outlook also depends on domestic inflation, central bank policy, trade conditions and the direction of international investment flows.
TradingView Currency Market Ticker
Follow selected currency pairs and the US Dollar Index using the market ticker below. The displayed market data are provided by TradingView and may be delayed depending on the instrument and data subscription.
What Currency Markets Will Watch Next
Several developments could influence Asian currencies in the coming sessions.
US Inflation and Federal Reserve Policy
New inflation and employment figures could change expectations for the Fed’s next interest rate decision. Any substantial movement in Treasury yields could affect the dollar and regional currencies.
Bank of Japan Policy Signals
Investors will assess whether Japan’s inflation, wage growth and domestic demand justify further interest rate increases. New policy guidance could influence expectations for the yen.
Australian Economic Data
Upcoming inflation and employment indicators will help investors assess the outlook following the RBA’s reported increase to 4.60%.
Chinese Market Reopening
Trading after the National Day holiday could offer further insight into investor positioning in the yuan and other Asian currencies.
South Korean Semiconductor Demand
Further evidence of sustained semiconductor demand could help investors evaluate South Korea’s export momentum and the potential implications for the won.
Ultimately, the interaction between interest rate differentials, economic releases and global capital flows remains central to the regional currency outlook. Strong economic data or a rate increase may support a currency, but neither guarantees appreciation when wider market conditions point in the opposite direction.
Key Takeaways
- The US Dollar Index was reported at 101.58, up 0.13%, following an approximately 2% gain during September.
- USD/JPY rose to around 158.15 as investors assessed differing BOJ views on future rate increases.
- Australia’s August trade surplus narrowed to A$495 million, while the RBA raised its cash rate to 4.60% on September 29.
- The Chinese yuan was relatively stable ahead of the mainland market holiday running through October 7.
- South Korean exports reportedly increased 83.5% year-on-year to a record US$120.9 billion, supported by semiconductor demand.
- Elevated US Treasury yields and uncertainty over central bank policy continued to influence Asian currency movements.
Frequently Asked Questions
Why is the US dollar strong against Asian currencies?
Elevated US Treasury yields and expectations for Federal Reserve policy can support demand for dollar-denominated assets. The dollar’s direction also depends on US economic data and developments in other economies.
Why did the Japanese yen weaken after the BOJ summary?
The summary revealed differing views among policymakers about economic conditions and the timing of future rate increases. Uncertainty over the pace of tightening can limit support for the yen, particularly when US yields remain elevated.
Does an Australian interest rate increase automatically strengthen the Australian dollar?
No. A rate increase can improve a currency’s relative yield, but the effect depends on market expectations, the central bank’s forward guidance, domestic economic data and movements in other currencies.
Why can the South Korean won weaken despite record exports?
Exchange rates respond to more than trade figures. Capital flows, hedging activity, relative interest rates and broad US dollar strength can offset the positive currency effects of strong exports.
What should currency market participants monitor next?
Key developments include US inflation and employment figures, BOJ policy communications, Australian economic releases, Chinese markets after the holiday and continued demand for South Korean semiconductor exports.
Related SkyPress Resources
- Latest Forex Markets News — currency movements and foreign exchange developments.
- SkyPress Forex Academy — educational resources on forex markets and trading fundamentals.
- Latest News — business, economic and global market developments.
Sources
- Bank of Japan — Summary of Opinions at the Monetary Policy Meeting on September 17 and 18, 2026, published October 1, 2026.
- Reserve Bank of Australia — monetary policy decision reported September 29, 2026.
- Yonhap News Agency — South Korean export figures reported October 1, 2026.
- Investing.com — regional currency market figures and commentary supplied for this report.
Market Disclaimer
This article is published by SkyPress for educational and informational purposes only. It does not constitute financial, investment or trading advice, or a recommendation to buy or sell any currency or financial instrument. Foreign exchange trading involves significant risk, and market prices can change rapidly. Readers should conduct independent research and consult a qualified financial professional where appropriate.
SkyPress Desk | SkyPress News