Markets Brace for October Fed Rate Hike as Barr Signals More Tightening

Stronger U.S. business activity and renewed inflation pressures have pushed expectations for another Federal Reserve rate increase higher.
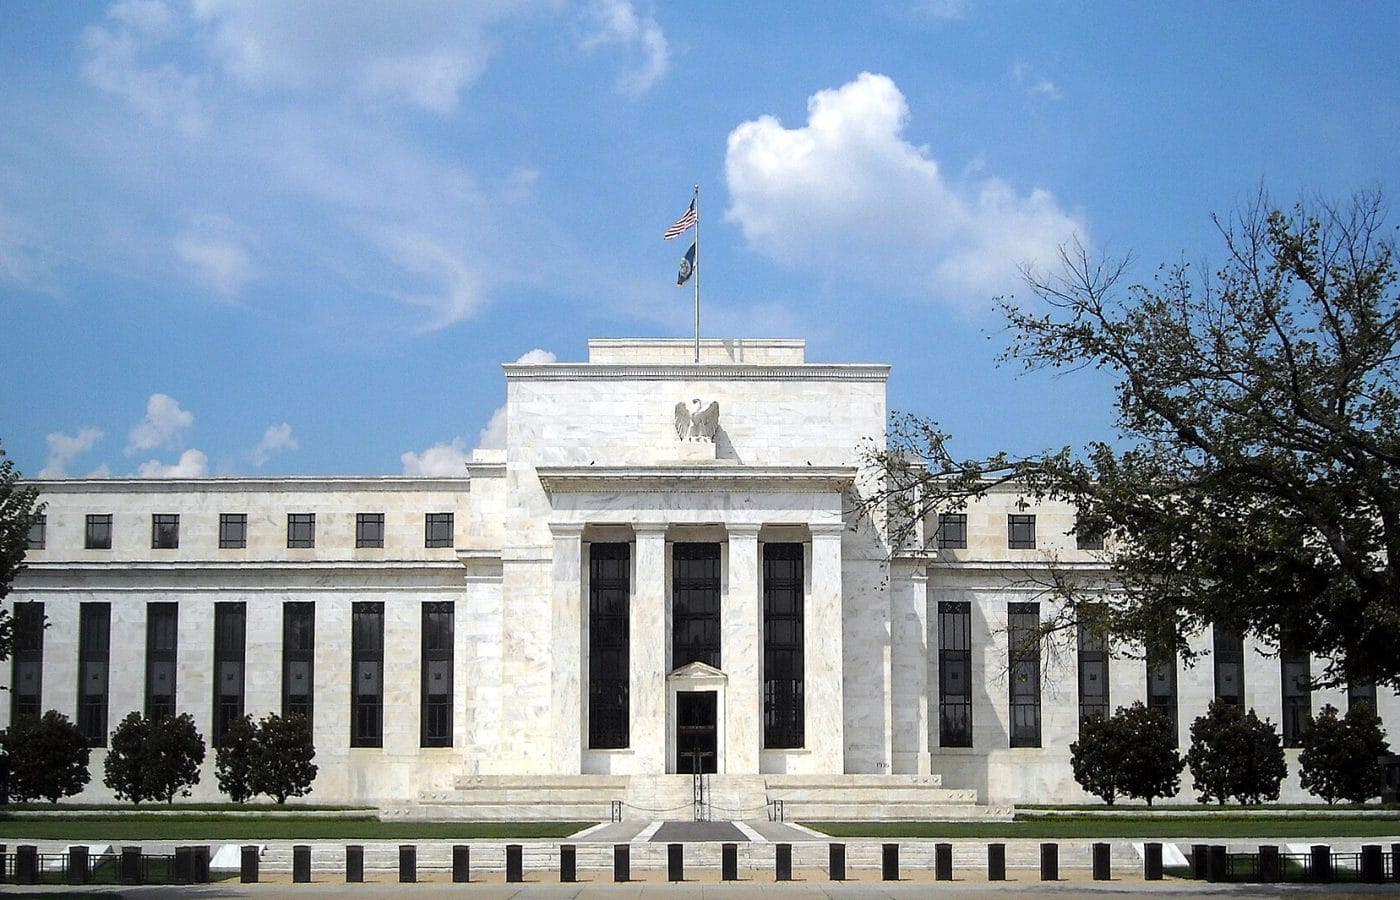
U.S. financial markets are increasingly pricing in the possibility of another Federal Reserve interest rate increase in October, after Federal Reserve Governor Michael Barr indicated that additional policy tightening could be necessary to bring inflation back toward the central bank’s 2% objective.
The shift in expectations came alongside stronger-than-expected September business activity data. Preliminary figures from S&P Global showed the U.S. private sector expanding at its fastest pace in more than five years, while measures of business input costs also accelerated.
The combination of resilient economic activity and renewed price pressures has added another layer of uncertainty to the Federal Reserve’s interest-rate path following its September policy decision.
Markets Increase Bets on an October Rate Increase
Interest-rate futures markets moved sharply on Wednesday as traders reassessed the likelihood of another Fed increase at the Federal Open Market Committee’s October 27–28 meeting.
According to CME FedWatch, market-implied expectations showed the probability of an October rate hike rising above 70% during Wednesday’s session. These probabilities are derived from Fed funds futures pricing and represent market expectations rather than a commitment by the Federal Reserve.
The move followed comments from Barr, who said the central bank may need to make further adjustments to monetary policy because inflation remains above target.
For investors and businesses, another rate increase would represent a continuation of the Fed’s renewed effort to restrain inflation after the central bank raised its benchmark policy rate by 25 basis points at its September meeting.
Barr Signals More Work May Be Needed on Inflation
Speaking at a housing affordability conference hosted by the Federal Reserve Bank of Chicago, Barr said inflation was not yet moving toward the Fed’s target quickly enough.
He also said the risks surrounding the inflation outlook had increased while risks to the labor market had receded, strengthening the case for adjusting monetary policy.
In his assessment, the Fed’s September decision was an important step toward recalibrating monetary policy. Barr indicated that additional policy adjustments could be required to ensure inflation returns to target in a timely manner.
The Federal Reserve’s official transcript of Barr’s remarks also noted that the U.S. economy remains strong and the labor market solid, while inflation remains above the central bank’s 2% target.
Barr’s comments are particularly significant because he is a Federal Reserve governor who participates in monetary-policy discussions. However, his comments should not be interpreted as a guarantee that the FOMC will raise rates in October. The committee will consider incoming inflation, employment, growth and financial-market data before making its decision.
U.S. Business Activity Accelerates Sharply
The rate-hike expectations were reinforced by a strong set of preliminary September business surveys from S&P Global.
The flash U.S. composite PMI increased to 58.4 in September from 56.0 in August. The reading marked the strongest expansion in private-sector activity since July 2021 and represented the fourth consecutive month of accelerating growth.
The services sector was a major contributor. The services business activity index rose to 58.7 from 56.5, reaching its highest level in almost five years.
Manufacturing activity also strengthened considerably. The manufacturing output index increased to 56.7 from 53.1, while the headline manufacturing PMI climbed to 57.0.
PMI readings above 50 indicate expansion, meaning the September figures pointed to broad-based growth across the U.S. private sector.
Stronger Growth Comes With Renewed Price Pressures
While stronger economic activity can support employment and business revenues, the latest PMI survey also highlighted an important challenge for the Federal Reserve: rising input costs.
S&P Global reported that input-cost inflation across the private sector accelerated to its fastest pace since October 2022. Higher fuel and transportation costs were among the factors pushing business costs higher, while wage pressures also increased in several areas.
Businesses also reported higher selling prices, suggesting that some of the increase in production costs could continue to filter through to consumers.
The combination of stronger demand, rising employment and higher business costs could make the inflation outlook more complicated for policymakers.
For a central bank attempting to bring inflation back toward 2%, stronger economic activity is not necessarily a problem by itself. The concern is whether sustained demand and higher costs could prevent inflation from easing as expected.
Employment Indicators Also Strengthen
The September surveys contained another notable development: companies reported stronger hiring as businesses worked through growing order backlogs.
S&P Global said employment increased at a pace not seen since 2022, while services-sector employment recorded its strongest expansion in more than two decades.
The improvement suggests that businesses are responding to stronger workloads by increasing staffing, adding another indication of resilience in the U.S. economy.
However, the employment data from the PMI survey is not equivalent to the official U.S. government employment report. Investors will therefore continue watching upcoming labor-market data for confirmation of the trend.
Treasury Yields Rise as Rate Expectations Shift
U.S. government bond yields also moved higher as traders adjusted expectations for monetary policy.
The two-year Treasury yield, which is particularly sensitive to expectations for the Federal Reserve’s policy rate, moved sharply higher during Wednesday’s session.
Higher short-term Treasury yields generally reflect expectations that interest rates could remain elevated for longer or rise further. Bond prices and yields move in opposite directions.
The move also has implications beyond the Treasury market. Higher U.S. yields can influence borrowing costs, currency markets, equities and commodities as investors reassess the relative attractiveness of dollar-denominated assets.
For more coverage of currency-market developments, see the SkyPress Forex Markets section.
What the Fed’s Next Decision Could Mean for Markets
The growing possibility of another rate increase is likely to keep monetary policy at the center of market discussions in the weeks ahead.
For the U.S. dollar, higher interest-rate expectations can provide support because higher yields may increase demand for dollar-denominated assets. However, currency movements are influenced by several factors, including economic data, global risk sentiment and expectations for other major central banks.
For stocks, higher interest rates can create a different set of pressures. Rising yields increase the cost of capital and can affect how investors value future corporate earnings. Technology and other growth-oriented companies can be particularly sensitive to changes in interest-rate expectations.
Bond markets are also likely to remain highly responsive to inflation and employment data as traders attempt to assess how far the Federal Reserve may need to go with monetary policy.
Oil Prices Add Another Inflation Risk
Energy prices are another factor that could influence the inflation outlook.
The September PMI survey indicated that fuel and transportation costs were already contributing to higher business input prices. Any sustained increase in crude oil prices could therefore add another source of inflationary pressure for businesses and consumers.
SkyPress has previously covered the impact of Middle East disruptions on crude markets, including the potential consequences for global supply and energy prices. Readers can follow the latest developments through our Commodities coverage and related oil-market analysis.
Housing Costs Remain Closely Linked to Interest Rates
The Federal Reserve’s policy outlook also has important implications for the housing market.
Mortgage rates generally respond to broader interest-rate and bond-market conditions, although they are influenced by more than the Fed’s short-term policy rate alone.
In his September 23 remarks, Barr highlighted the continued affordability challenges facing U.S. households. He noted that high home prices and elevated mortgage rates have made homeownership more difficult for many families.
The Federal Reserve’s housing analysis also pointed to the interaction between housing supply, home prices, mortgage rates and household incomes. Barr said the Atlanta Fed’s affordability measure fell to 68 in July 2026, its lowest level in 21 years.
For broader analysis of international housing markets, affordability and interest rates, see the SkyPress real-estate pillar: Global Housing Market Trends, Prices, Affordability and Real Estate Outlook.
Why the October Fed Meeting Matters
The Federal Reserve’s next scheduled policy meeting is set for October 27–28, 2026. Until then, markets will continue to receive additional information about inflation, employment, consumer activity and economic growth.
The latest developments have changed the market’s assessment of the October meeting, but the final decision will depend on the data and the views of the Federal Open Market Committee at the time of the meeting.
The September PMI data provides evidence of strong economic momentum, while the increase in business input costs highlights continued inflation risks. Together with Barr’s comments, these developments have caused traders to place greater emphasis on the possibility of additional monetary tightening.
Key Takeaways
- Markets increased expectations for another Federal Reserve rate hike in October.
- Fed Governor Michael Barr said further policy adjustments may be needed to bring inflation back toward the central bank’s 2% target.
- The S&P Global U.S. flash composite PMI rose to 58.4 in September from 56.0 in August.
- The services index increased to 58.7, while manufacturing output rose to 56.7.
- Business input costs increased at their fastest pace since October 2022, according to the PMI survey.
- Employment growth also strengthened as companies worked through rising order backlogs.
- Higher rate expectations pushed Treasury yields higher and increased market attention on the U.S. dollar, equities and bonds.
- The October 27–28 FOMC meeting will be a key event for markets as policymakers assess incoming economic data.
What to Watch Next
Markets will now focus on upcoming U.S. inflation, employment, consumer and growth indicators for further clues about the Federal Reserve’s policy direction.
Investors will also monitor Treasury yields, the U.S. dollar, equities and commodity prices because changes in interest-rate expectations can quickly spread across global financial markets.
For continuing coverage, visit SkyPress Latest News for economic developments and market-moving stories, or explore our Forex Markets section for currency-market coverage.
Article Disclaimer
This article is provided for educational and informational purposes only and should not be considered financial, investment or trading advice. Market prices can move rapidly and may be affected by economic data, geopolitical developments, monetary policy and other factors. Readers should conduct their own research and consider seeking advice from a qualified professional before making financial decisions.
Sources
- Federal Reserve — Governor Michael S. Barr, September 23, 2026
- CME Group — FedWatch
- S&P Global — September 2026 U.S. Flash PMI data
- Reuters — Federal Reserve Governor Michael Barr’s September 23 remarks