RBA Warns Inflation Risks Are Building as Energy Prices and Domestic Demand Stay High

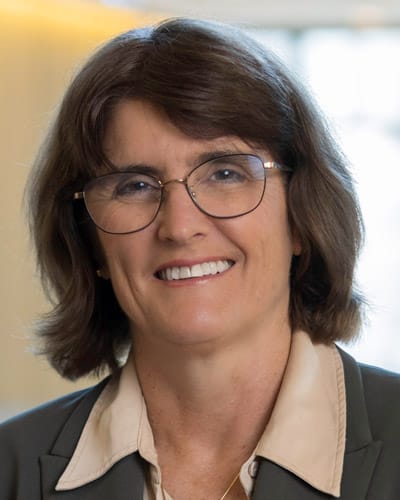
SYDNEY, September 22, 2026 — Reserve Bank of Australia Governor Michele Bullock has warned that inflation risks in Australia may be becoming more persistent, pointing to elevated energy prices and continued strength in domestic demand ahead of the central bank’s September monetary policy meeting.
Speaking at a Committee for Economic Development of Australia (CEDA) event in Sydney on Tuesday, Bullock highlighted the continuing effects of the Middle East conflict on energy markets while also stressing that domestic demand remains stronger than the economy’s ability to supply goods and services.
Her comments come one week before the RBA is scheduled to announce its next interest-rate decision on September 29, placing renewed attention on whether the central bank will tighten monetary policy again.
Energy Prices Add to Australia’s Inflation Challenge
The RBA governor identified the prolonged Middle East conflict and its impact on energy prices as an important source of inflation risk.
Higher energy costs can affect the Australian economy through several channels. In addition to directly increasing household fuel and utility expenses, higher energy prices can raise transportation, manufacturing and business operating costs. Those costs can eventually be passed through to consumers in the form of higher prices.
Reuters reported that Bullock said upside risks to inflation may be materialising as energy prices have remained elevated and excess demand continues within the domestic economy.
The RBA has previously warned that the conflict could create stronger and more persistent price pressures if higher global commodity costs are passed through more broadly into Australian consumer prices.
In its August Statement on Monetary Policy, the central bank said inflation remained elevated because of a combination of domestic capacity pressures and higher input costs associated with the Middle East conflict.
Australian Inflation Remains Above the RBA’s Target
Recent official data show why inflation remains a concern for policymakers.
According to the Australian Bureau of Statistics, consumer prices increased 3.5% in the year to July 2026, down from 3.8% in June. However, trimmed-mean inflation, an important measure of underlying price pressures watched by the RBA, remained at 3.6%.
Both measures remain above the RBA’s 2% to 3% inflation target range, suggesting that underlying price pressures have not yet returned to levels consistent with the central bank’s objective.
The RBA’s August projections indicated that inflation would take time to return sustainably toward the middle of its target range. The central bank also warned that a more persistent Middle East conflict, stronger global oil-price pressures or greater domestic capacity pressures could produce a more difficult inflation path.
Domestic Demand Is Another Source of Pressure
Energy prices are not the only issue confronting policymakers.
Bullock also pointed to excess demand in the Australian economy. When demand for goods and services remains stronger than the economy’s ability to supply them, businesses can face greater pressure to increase prices.
This dynamic is particularly important for the RBA because interest rates are one of its main tools for influencing household spending, borrowing and investment.
The central bank has already raised interest rates three times in 2026, increasing the cash rate by a cumulative 75 basis points to 4.35%. The RBA left the rate unchanged at its August meeting while assessing the effects of the earlier increases.
The latest RBA cash-rate information shows the target remains at 4.35%, with the next policy update scheduled for September 29.
Labour Market Could Need to Cool Further
Bullock also highlighted the relationship between employment conditions, economic capacity and inflation.
The Australian labour market has remained relatively strong, although conditions have begun to ease. The ABS reported an unemployment rate of 4.5% in July, while employment fell by 16,000 people during the month.
For policymakers, a modest increase in unemployment can reduce pressure on wages and overall demand. Bullock indicated that an unemployment rate in the range of roughly 4.5% to 5.0% could be consistent with the process of bringing inflation down.
That does not mean the RBA is targeting unemployment for its own sake. Rather, the central bank is balancing employment conditions against its responsibility to return inflation to target.
The RBA’s August forecasts already anticipated a gradual increase in unemployment as tighter financial conditions work through the economy. Its projections showed unemployment rising toward the upper part of the 4% range over the forecast period.
Bullock Does Not Pre-Commit to a September Rate Hike
Despite the increasingly cautious tone from the RBA, Bullock did not signal that the central bank had already decided to raise interest rates at its September meeting.
Instead, her remarks focused on the risks surrounding the inflation outlook and the need for policymakers to assess incoming economic information.
This distinction is important. Central banks frequently discuss risks to inflation without committing themselves to a specific policy decision. The final decision will depend on the information available to the Monetary Policy Board when it meets.
The RBA’s own calendar confirms that the next monetary policy decision is scheduled for September 29, 2026.
Sarah Hunter Also Keeps Further Tightening on the Table
Comments from RBA Assistant Governor Sarah Hunter have added to the focus on the possibility of another rate increase.
In a recent interview published by the RBA on September 22, Hunter discussed the way external shocks such as oil-price increases can feed into Australian inflation and explained that monetary policy may respond to those pressures in order to prevent inflation from becoming entrenched.
Hunter also emphasized that the RBA closely monitors household financial conditions and potential signs of mortgage stress when assessing the impact of higher interest rates.
Her comments underline the difficult balance facing policymakers: interest rates may need to remain restrictive enough to contain inflation, while excessive tightening could place additional pressure on households and interest-sensitive parts of the economy.
Markets Watch for Another 25-Basis-Point Increase
Financial markets have increasingly focused on the possibility of another rate increase at the September meeting.
Reuters reported that markets were pricing a high probability of a further 25-basis-point increase, which would take the cash rate from 4.35% to 4.60% if the RBA were to act.
Market pricing, however, is not the same as an RBA decision. The central bank has repeatedly emphasized that monetary policy decisions depend on the evolving economic outlook and incoming data.
Investors are therefore likely to pay close attention to inflation, employment, household spending and energy-price developments ahead of the September 29 decision.
What Another Rate Increase Would Mean for Australia
A further increase in the cash rate would raise borrowing costs across parts of the economy, particularly for households with variable-rate mortgages and businesses dependent on credit.
Higher interest rates can reduce disposable income available for household spending and increase the cost of servicing debt. Over time, weaker demand can reduce the ability of businesses to raise prices and help bring inflation closer to the RBA’s target.
However, energy-driven inflation presents a more complicated challenge because some of the initial pressure comes from global supply conditions rather than domestic demand.
This creates a policy trade-off for the RBA. Monetary tightening can weaken domestic demand, but it cannot directly increase global oil production or immediately resolve geopolitical disruptions affecting energy markets.
The RBA has acknowledged this distinction in its economic assessments, noting that higher energy and input costs from the Middle East conflict are occurring alongside domestic capacity pressures.
Australian Households Face a More Complicated Interest-Rate Environment
For Australian households, the renewed inflation concerns come after several interest-rate increases earlier in the year.
The RBA has already lifted borrowing costs by 75 basis points during 2026. Although the central bank paused in August, the possibility of another increase means mortgage holders and other borrowers remain exposed to changes in monetary policy.
At the same time, households continue to face elevated prices for essential goods and services. The July CPI data showed housing prices were among the largest contributors to annual inflation, with housing costs rising 5.0% over the year.
The combination of higher borrowing costs and elevated living expenses could therefore remain an important consideration for households as the RBA approaches its next decision.
Why the September RBA Decision Matters
The September 29 meeting comes at an important point for Australia’s inflation outlook.
The RBA is attempting to determine whether the interest-rate increases already delivered are sufficiently slowing domestic demand, or whether persistent inflation risks require additional policy tightening.
At the same time, developments in global energy markets could complicate the inflation outlook. A prolonged disruption in oil and gas markets could keep costs elevated even as domestic demand begins to moderate.
The RBA’s August forecasts anticipated that inflation would gradually decline as tighter financial conditions reduce capacity pressures and conflict-related cost pressures ease. But the central bank also identified the possibility that those risks could prove more persistent than expected.
What to Watch Before the Decision
Markets and households will be watching several developments before the RBA announces its decision:
- Inflation: Whether underlying price pressures continue to ease or remain above the RBA’s target range.
- Energy prices: Whether global oil and gas prices remain elevated because of geopolitical developments.
- Household spending: Whether higher borrowing costs are beginning to materially weaken domestic demand.
- Employment: Whether labour-market conditions continue to loosen from their relatively tight levels.
- Wages: Whether wage growth remains consistent with inflation returning to target.
- Financial stress: Whether higher borrowing costs are creating significant pressure for households and businesses.
The ABS is also scheduled to release Australia’s August labour-market data on September 24, five days before the RBA’s policy decision. That release could provide policymakers and markets with another important indicator of how the economy is performing.
SkyPress Market Perspective
The latest RBA communication suggests that Australia’s inflation challenge is no longer being viewed solely through the lens of domestic demand.
Global energy prices, geopolitical developments and domestic economic capacity are interacting at the same time. That makes the policy environment more complicated than a conventional inflation cycle driven primarily by household spending.
With the cash rate already at 4.35%, the September 29 decision will provide an important signal about how the RBA assesses the balance between persistent inflation and the effects of earlier monetary tightening.
For financial markets, the Australian dollar, government bond yields, bank stocks and interest-rate-sensitive sectors could all respond to changes in expectations surrounding the RBA’s policy path. For households, the outcome will be particularly relevant to mortgage costs, borrowing conditions and the broader cost of living.
However, the central bank’s latest comments do not amount to a pre-announced rate decision. The final outcome will depend on the economic information available to the Monetary Policy Board at its September meeting.
Key Takeaways
- RBA Governor Michele Bullock says inflation risks may be becoming more persistent.
- High energy prices linked to the prolonged Middle East conflict remain an important risk.
- Domestic demand is also continuing to contribute to inflationary pressure.
- Australia’s July CPI rose 3.5% annually, while trimmed-mean inflation remained at 3.6%.
- The RBA’s cash rate remains at 4.35% after three increases totaling 75 basis points in 2026.
- The next RBA monetary policy decision is scheduled for September 29.
- Markets are watching closely for the possibility of another 25-basis-point increase, although market pricing does not represent a confirmed RBA decision.
- Australia’s August employment report, due September 24, will provide another important economic indicator before the RBA meeting.
Sources
Reserve Bank of Australia — monetary policy statements, cash-rate information, economic outlook and speeches.
Australian Bureau of Statistics — Consumer Price Index and Labour Force data.
Reuters — September 22, 2026 reporting on RBA inflation risks and market expectations.
Article Disclaimer
This SkyPress article is provided for general educational and informational purposes only. It is not financial, investment, trading or economic advice. Market conditions can change rapidly, and readers should conduct their own research and consult a qualified professional before making financial decisions.
SkyPress by Skyrexx
SkyPress provides practical financial education, market news and economic insights for a global audience. Our news coverage is intended to help readers understand important developments across financial markets and the global economy.
© 2026 SkyPress by Skyrexx. All rights reserved.